How improvements fit into a jumbo loan appraisal
A jumbo loan appraisal is an independent opinion of a property's market value for a specific transaction. Renovation spending does not automatically translate into the same amount of added value: the appraiser considers the home as it exists on the appraisal's effective date and compares its condition, features, and location with relevant sales and other market evidence.
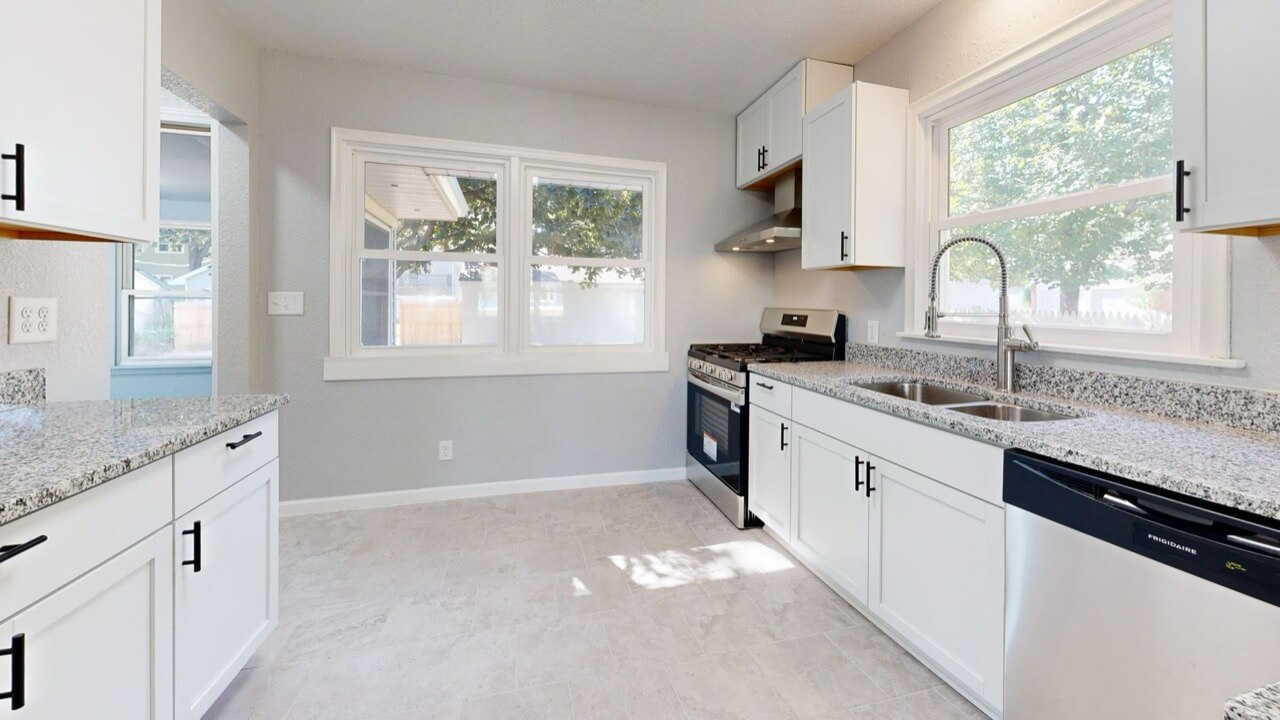
Completed improvements may matter when their quality, functionality, and condition influence how buyers respond to a property. A permitted addition, substantial kitchen renovation, or upgraded major system may help distinguish a home, while routine repairs may simply address maintenance. Luxury features also have no automatic dollar value; their contribution depends on the property and available comparable sales.
Organized records can help communicate what work was done and when. Plans, permits, receipts, contractor details, and final sign-offs may clarify features that are not obvious during a walkthrough. They document the work, not what the market will pay for it. The appraiser independently determines what information is relevant, and the lender separately reviews the appraisal, borrower, loan terms, and property eligibility. Approval and terms remain subject to credit approval and program guidelines.
Completed work and unfinished or proposed work may be handled differently under the assignment and loan requirements. If a report contains a factual error, borrowers can raise specific questions and provide supporting records through the lender's process. The goal is to clarify accurate information, not to seek a predetermined value.
Questions about your situation?
Talk it through with a loan officer who knows this market. No forms and no pressure.
Newport Beach's distinctive value landscape
Newport Beach's Zillow Research estimate puts the local home value at $3,697,219 in August 2026. For a jumbo appraisal, that market context makes the home's specific features and suitable comparable sales especially important; renovation cost alone cannot establish its value.
Comparable sales matter in a high-cost market
The median home value for Orange County was $915,500, according to the Census ACS 5-Year, 2023. Newport Beach's local Zillow Research estimate is substantially higher, so a countywide midpoint may not describe a distinctive property or provide the right comparison for its appraisal.
For one-unit properties in Orange County, the 2026 conforming loan limit is $1,249,125, according to FHFA Conforming Loan Limits, 2026. A requested loan above the applicable limit may fall into jumbo financing; the appraisal still evaluates the property using relevant market evidence rather than renovation receipts. I review the appraisal and improvement records with the borrower, flag questions that may need clarification, and keep the borrower updated as the lender's review moves forward. I go through what the report says, identify factual details to check, and explain what information may be useful to submit through the appropriate process.
What I see in this market
Quality upgrades, such as a remodeled kitchen, additional living space, or enhancements that offer ocean views, can significantly boost a jumbo appraisal in Newport Beach. However, it's important to be cautious about unpermitted work, as it can create complications during the appraisal process. Highly personalized features may not add much value and could even raise concerns for lenders. As a borrower, understanding these nuances is crucial to ensure that your property meets the necessary standards and expectations in the market.
Market pace and evidence for a distinctive home
Newport Beach homes took 43 days to go pending, according to Zillow Research, August 2026. That market timing is useful context, but it does not predict an individual appraisal result. When a renovation creates unusual features, the availability and fit of comparable sales remain central to the appraiser's analysis.
In Newport Beach, 22.24% of listings had price cuts, according to Zillow Research, August 2026. This is a reason not to treat an asking price—or a renovation budget—as proof of value. Share accurate details about completed work and let the appraiser weigh them against market evidence.
What the wider price range means for appraisal records
Newport Beach's starter home value was $1,928,506 in Zillow Research, August 2026, while its top-tier home value was $6,877,464 in Zillow Research, August 2026. That spread underscores why a general neighborhood price or a home's project costs cannot substitute for comparisons suited to its particular location, design, condition, and features.
For a home with a distinctive renovation, prepare a concise record of completed work and clearly separate it from planned or unfinished projects. That gives the lender's appraisal process useful factual context without suggesting a required valuation.
What exactly is a conventional loan?
A conventional loan is a mortgage that is not insured or guaranteed by a government agency; it may be conforming or jumbo, depending on the loan and applicable limits. In Orange County, the 2026 one-unit conforming limit is $1,249,125, according to FHFA Conforming Loan Limits, 2026. In Newport Beach, a jumbo appraisal still considers the individual property's market evidence, including relevant comparable sales and completed improvements.
Are conventional loans better?
Not universally: whether a conventional loan is a better fit depends on the borrower's finances, the property, and the loan terms. For a Newport Beach buyer seeking a jumbo loan, the appraisal is a separate consideration: the local home value was $3,697,219 in Zillow Research, August 2026, while the one-unit Orange County conforming limit is $1,249,125, according to FHFA Conforming Loan Limits, 2026. Those figures provide market and loan-limit context, not a prediction of an individual home's appraised value.
Part of this series
The numbers behind this page
Every figure comes from public data on Newport Beach, CA and Orange County. Each one names its source and the month it describes, so you can check it yourself.
